Best Stocks Under 200: 8 NSE/BSE Picks by Use-Case
Explore 8 best stocks under 200 across NSE and BSE, grouped by sector and use-case, with risk notes, recent performance and liquidity checks.
What does a share price below ₹200 tell you? This list covers eight publicly discussed NSE/BSE companies with shares below ₹200 in the supplied reference ranges, but a low price alone doesn't establish value. Investors still need to compare business quality, financial metrics, liquidity and risk before drawing conclusions.
The phrase best stocks under 200 can suggest affordability, but share price is only the price of one unit of ownership. It says little by itself about a company's market value, debt, cash generation or future earnings. Historical NSE and BSE records make long-run analysis possible, with NSE providing security-wise price-volume archives and BSE offering historical prices reaching back to 1988–1990 through its market-data resources, as documented in this Indian stocks under ₹200 reference.
The reference price ranges used for this educational roundup are historical. They must be rechecked against current NSE/BSE prices, corporate actions, trading volume and bid-ask spreads before publication or any decision. Liquidity means how easily you can transact without materially moving the market price. A share may appear inexpensive but still be difficult to trade at a desired price.
The eight names are grouped by use-case and sector, not presented as recommendations. Coal India provides dividend context. HDFC Bank, Infosys, Wipro and Reliance Industries offer quality, growth or diversification angles. Tata Steel and Maruti Suzuki represent cyclical exposure, while Bajaj Auto provides operating-resilience and momentum context. NSE price bands can commonly be set at 2%, 5%, 10% or 20% either way, and derivative-linked securities may have no price band, making exchange rules relevant to risk management for lower-priced shares (NSE price-band information).
SEBI rules require anyone acting as or presenting themselves as a research analyst to obtain SEBI registration (SEBI Research Analysts Regulations). This is for informational and educational purposes only and not investment advice. Consult a SEBI-registered adviser before investing.
Table of Contents
- 1. Tata Steel Limited and cyclical infrastructure exposure
- 2. Bajaj Auto Limited and operating resilience
- 3. Coal India Limited and the dividend lens
- 4. HDFC Bank Limited and private-banking quality
- 5. Infosys Limited and technology-led growth
- 6. Maruti Suzuki India Limited and auto-cycle exposure
- 7. Wipro Limited and specialised IT execution
- 8. Reliance Industries Limited and diversified exposure
- Top 8 Stocks Under 200, Comparative Snapshot
- Build a Repeatable ₹200 Stock Research Check
1. Tata Steel Limited and cyclical infrastructure exposure
Tata Steel sits firmly in the cyclical part of the under-₹200 universe. Its business is linked to steel demand from automotive, construction and infrastructure, so the investment case depends less on the nominal share price and more on the relationship between selling prices, raw-material costs, production efficiency and balance-sheet strength.
The company operates across flat products, long products and tubes. That range gives it exposure to several industrial applications, but it also leaves earnings sensitive to commodity cycles. Steel prices can weaken when supply rises or construction and manufacturing activity slows. Iron ore and coking coal costs can then compress margins even when volumes remain steady.
What to monitor in a steel cycle
Quarterly capacity utilisation helps indicate how effectively plants are being used. Realisation, the average selling price earned per tonne, shows whether stronger demand is translating into revenue quality rather than just higher dispatches. Investors examining the company's results should compare both measures instead of relying on sales growth alone.
Debt is another central variable. A steel producer can report strong operating performance while interest costs and capital expenditure place pressure on equity cash flows. Reviewing the debt-to-equity ratio each quarter can help readers assess whether deleveraging is supporting the business or whether expansion is increasing financial risk.
Practical rule: For a cyclical steel company, track the spread between selling realisations and iron ore or coking coal costs, not just the share price.
Global commodity prices also matter because domestic infrastructure optimism doesn't eliminate international volatility. Sector rotation can change how cyclical shares trade, which makes Bharatstox's sector rotation chart useful as an educational reference rather than a timing signal.
2. Bajaj Auto Limited and operating resilience
Bajaj Auto offers a different lens on the under-₹200 discussion. Its earnings are linked to two-wheelers, three-wheelers and commercial vehicles, with operating performance influenced by product mix, export demand, input costs and the pace of electrification.
The company is India's second-largest two-wheeler manufacturer and has about 18% market share in motorcycles and scooters, according to the supplied company profile (Bajaj Auto market-screen reference). That position can support distribution, brand visibility and scale, although market leadership doesn't remove the risk of changing consumer preferences or weak rural and urban demand.
The operating indicators matter more than the price label
Export volumes deserve close attention because they can materially affect the business's geographic mix. Average realisation per unit helps show whether revenue is rising through pricing and premium products, or through higher dispatches alone. A stronger product mix can support margins, but it can also make the company more exposed to specific segments.
Motorcycles and scooters should be assessed separately. Bajaj Auto's motorcycle focus is a structural feature of its portfolio, while the electric two-wheeler market introduces a separate competitive test. Chetak volumes and adoption trends can help readers evaluate whether the company is building an effective position in electric mobility.
Liquidity checks remain essential. A trader looking at momentum should confirm current turnover, market depth and the bid-ask spread on the relevant exchange. Historical outperformance, if reported elsewhere, doesn't establish that the same trading conditions exist today.
The key risk is execution. Bajaj Auto may benefit from cost discipline and efficiency gains, but product launches, export demand and electric-vehicle adoption can change the earnings profile quickly. A price below ₹200, if observed in a historical screen, should therefore be treated as a starting filter, not a conclusion.
3. Coal India Limited and the dividend lens
Coal India is best understood through cash distribution and energy demand rather than through a generic growth-stock framework. The company is the world's largest coal mining company by output and has a near-monopoly in India's domestic coal supply, with about 80% market share, based on the supplied reference material (Coal India stock screen).
That position gives the business defensive exposure to thermal power demand. Power-plant utilisation, coal production and the average realisation per tonne are more informative indicators than the share price alone. If output rises but realisation weakens, revenue quality may not improve proportionately. If demand strengthens but production fails to keep pace, operational constraints can become visible in supply data.
Why dividend analysis needs more than a yield figure
Dividend yield compares annual dividends with the share price. It can look attractive when the price falls, but that doesn't mean the dividend is permanent. Readers should examine per-share payouts, payment dates, operating cash flow and the company's capital requirements before treating a distribution as a durable feature.
Coal India's principal risk is concentration. Its earnings are tied to thermal coal demand, policy, environmental regulation and the operating performance of power generators. A near-monopoly can strengthen market position, but it doesn't guarantee uninterrupted production or stable cash distributions.
For readers learning how corporate actions affect apparent affordability, Bharatstox's guide to corporate action events explains why dividends, splits and bonuses need to be recorded when comparing historical prices. The exchange framework also matters. NSE notes that 20% price bands apply to the auction market, while some derivative-linked securities operate under a 10% range to curb non-genuine orders (NSE price-band explanation).
Coal India may suit a dividend-focused analytical category, but that label isn't a promise of yield or capital preservation. Dividend income can vary, and the share can still respond sharply to policy, commodity and market-wide changes.
4. HDFC Bank Limited and private-banking quality
HDFC Bank belongs in an under-₹200 discussion because it shows why nominal price can be misleading. The bank is India's largest private-sector bank by assets and market capitalisation, and the supplied reference describes the merged HDFC entity as systemically important, with significant brand strength and digital capabilities.
For a bank, quality analysis starts with the balance sheet. Loan growth can support earnings, but deposits provide the funding base. A sustained divergence between advances growth and deposit growth may indicate pressure on funding costs or liquidity. The direction of net interest margin, or NIM, also matters because it shows the spread between lending income and funding costs.
A bank's risk is hidden in credit metrics
Gross and net non-performing assets, or NPAs, help indicate the level of stressed loans before and after provisions. Rising NPAs can force a bank to set aside more money against potential losses. Capital adequacy shows whether the bank has a sufficient capital cushion to absorb stress while continuing to expand.
The supplied monitoring framework flags NIM compression below 4.0% as a warning threshold (HDFC Bank stock-screen context). That figure should be treated as a screening reference, not an automatic verdict. Investors need to examine the bank's reported mix, funding conditions and peer comparison at the same date.
A low bank share price doesn't make a loan book safer. Credit quality, provisioning and capital determine how much risk sits behind the valuation.
The merger with HDFC changed the scale and structure of the combined institution, so older financial ratios may not be directly comparable with newer periods. Readers should note the reporting basis and read accompanying explanations. Bharatstox's guide on how to read an Indian annual report can help newer investors locate balance-sheet, cash-flow and management commentary sections.
Liquidity can be strong in large banking names, but it still changes by session and market conditions. The relevant question isn't whether the stock is below ₹200. It's whether the current price reflects sustainable earnings, asset quality and the cost of funding.
5. Infosys Limited and technology-led growth
Infosys represents the export-oriented technology-services angle. The company is India's second-largest IT services provider, with substantial exposure to the United States and a diversified client base across sectors. That global reach creates growth opportunities, but it also exposes revenue to corporate technology budgets, currency movements and wage costs.
The operating model is people-intensive. Utilisation, or the proportion of employees assigned to billable work, affects margins because unallocated staff still generate costs. Billing rates, large deal wins and the health of the deal pipeline help readers judge whether demand is improving in a durable way or only through short-term project activity.
Currency and talent are central risks
Dollar-rupee movements affect reported revenue in rupee terms. A stronger rupee can reduce the value of overseas revenue after conversion, even if clients pay the same amount in dollars. Attrition also matters. When employees leave at a high rate, replacement hiring and wage pressure can reduce profitability.
Infosys faces a familiar tension in technology services. Clients may delay discretionary spending during uncertain economic periods, while the company still needs to invest in cloud capabilities, cybersecurity, artificial intelligence and employee skills. Margin recovery can come from improved utilisation, better pricing or moderated wage inflation, but each depends on execution and demand.
Investors comparing Infosys with other IT names should examine revenue growth, operating margin, cash conversion and client concentration on the same reporting dates. The equity research explainer from Bharatstox provides background on how analysts organise that work, but readers should distinguish analysis from a personalised recommendation.
The stock's position in a historical under-₹200 range doesn't determine whether its growth profile is attractive. Valuation depends on expected earnings, business resilience and the price paid for those earnings. Liquidity may be easier to verify in a large, widely followed company, but bid-ask spreads and volume still need to be checked in real time.
6. Maruti Suzuki India Limited and auto-cycle exposure
Maruti Suzuki is a consumer and manufacturing business whose performance moves with vehicle demand, household income, financing conditions and input costs. It is India's largest passenger-car manufacturer, with about 40% market share in four-wheelers, according to the supplied company profile (Maruti Suzuki under-₹200 reference).
The company benefits from low-cost manufacturing, a broad dealer network and a strong position in compact and mid-segment vehicles. Scale can improve purchasing power and production efficiency, but it doesn't eliminate competition. Consumer preferences can shift between vehicle types, fuel technologies and price points faster than factories can adjust.
Volume, pricing and materials tell different stories
Quarterly vehicle volumes show demand. Average selling price indicates whether the company is moving towards higher-value models or relying mainly on unit growth. Raw materials such as steel, aluminium and plastics influence margins, while industry capacity utilisation affects pricing power.
Capacity utilisation above 70% is identified in the supplied monitoring framework as a level at which pricing power can improve (Maruti Suzuki stock-screen context). It's a useful analytical reference, not a guaranteed margin outcome. Competition, discounts and product mix can still offset higher factory utilisation.
EV transition risk deserves separate attention. Launch timelines, product acceptance and pre-orders may indicate how quickly the company is adapting, but early interest doesn't automatically translate into profitable scale. The existing internal-combustion portfolio can remain important while the market evolves, creating a capital-allocation challenge.
A reader comparing Maruti Suzuki with cyclical names should separate business quality from timing. Auto shares can respond to interest rates, festival demand, fuel prices and monthly registrations. The under-₹200 filter identifies a price range, but it doesn't reveal whether the current cycle is favourable or whether the market already discounts stronger earnings.
7. Wipro Limited and specialised IT execution
Wipro offers exposure to technology services, particularly cloud, cybersecurity and analytics. Its performance depends less on the share-price screen than on whether it converts specialist capabilities into profitable, repeatable delivery. Client concentration, pricing pressure and cost-control execution remain material risks.
A useful dashboard combines utilisation, billing rates, operating margin, cost per employee and attrition. Rising cost per employee can weaken margins unless billing rates or productivity improve. High attrition increases recruitment and training costs, while low utilisation leaves more staff without billable assignments. These indicators should be read together, because one strong quarter does not establish a durable trend.
Cloud and cybersecurity revenue also need separate examination. Their demand, staffing requirements and pricing can differ from legacy services, so headline revenue growth may not show whether the mix is becoming more profitable. Cloud-revenue share, where disclosed, helps identify business composition, while delivery costs show how much of that growth reaches the margin line.
Contract visibility is not earnings visibility
The supplied monitoring notes identify contracts above $50 million as a visibility indicator (Wipro stock-screen reference). The threshold supports screening, not a profitability conclusion. Contract duration, scope, pricing, employee requirements and implementation costs determine its financial value.
A large cloud transformation award can still produce uneven results if implementation is delayed or the client controls spending. Cybersecurity work may require scarce specialists, raising staffing costs and reducing the benefit of the contract. These execution risks make order size less informative when separated from utilisation, attrition and margin trends.
Wipro therefore fits a specialised IT-execution lens rather than a simple low-price or momentum label. Active investors may find trading activity relevant, while Bharatstox's market journalism and timestamped reporting can help track sector rotation and company announcements. Readers should separate reported developments from analyst interpretation before forming their own view.
8. Reliance Industries Limited and diversified exposure
Reliance Industries combines several businesses that respond to different economic drivers. Its operations span oil and gas, petrochemicals, refining, retail, telecom and renewables. That mix can reduce reliance on one earnings stream, but it also makes valuation more complex because commodity earnings, consumer businesses and capital-intensive expansion need different measures.
Refining and petrochemicals remain linked to global conditions. Brent crude prices and refining margins, the spread between product values and crude input costs, influence the energy businesses. Retail and telecom require different indicators, including revenue growth, customer economics and cash generation. Renewable expansion adds another capital-allocation question.
Separate the mature cash engines from the growth options
Reliance's retail and Jio businesses are often assessed for future growth, but readers should distinguish operating progress from expectations already reflected in the valuation. The supplied profile cites management's projected profitability target for Jio Mart by FY26, which is a forward-looking company objective and should be treated as a projection, not an established result (Reliance Industries stock-screen reference).
Renewables require similar discipline. Capacity additions measured in megawatts, related capital expenditure and the eventual cash returns should be tracked separately. Heavy investment can create long-term opportunities while increasing debt and execution risk in the near term.
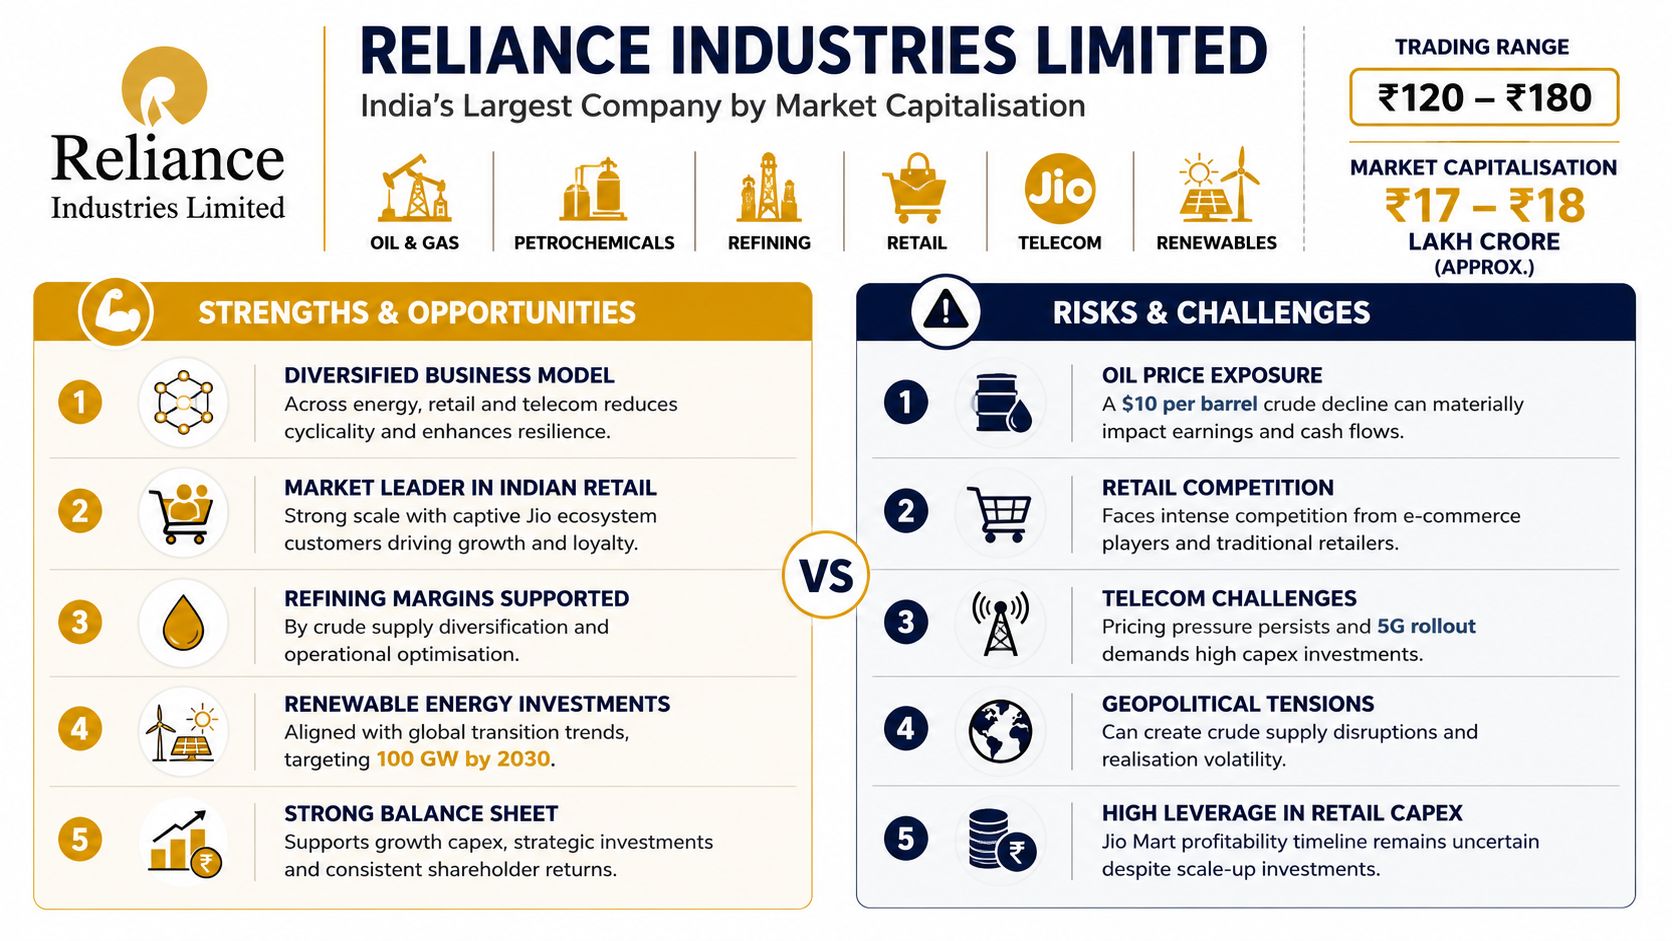
Debt-to-equity deserves particular attention as retail and renewable capex scales. Investors should also read segment reporting because consolidated revenue can conceal differing margins and capital requirements. An integrated group may gain from internal capabilities and scale, but diversification doesn't guarantee that every division will perform well at the same time.
Reliance is included here for diversified exposure analysis, not as a recommendation. Its nominal price in any historical reference range must be checked against corporate actions and current exchange data. The company's size may support liquidity, yet even liquid shares can experience changing spreads and volatility around results, policy news and global commodity moves.
Top 8 Stocks Under 200, Comparative Snapshot
| Investment | 🔄 Implementation Complexity | ⚡ Resource Requirements | ⭐ Expected Outcomes / 📊 Impact | 💡 Ideal Use Cases / Key Advantages |
|---|---|---|---|---|
| Tata Steel Limited – Cyclical Play in Infrastructure Recovery | High 🔄 (integrated operations + European footprint) | High ⚡ (capex, raw materials, working capital) | ⭐⭐⭐ 📊 Cyclical upside if spreads & utilization (>70%) recover; earnings volatile | Infrastructure recovery play; dividend income potential; monitor iron‑ore/coal prices & utilization 💡 |
| Bajaj Auto Limited – Two‑Wheeler Market Leader with Margin Expansion | Moderate 🔄 (product mix, export markets, EV transition) | Moderate ⚡ (R&D for EVs, working capital) | ⭐⭐⭐⭐ 📊 Stable margins with premium mix and export resilience; moderate growth | Premium two‑wheeler exposure; margin expansion + cash returns; track export volumes, ASPs, Chetak EV adoption 💡 |
| Coal India Limited – Thermal Coal Supply Monopoly with Dividend Focus | Low–Moderate 🔄 (regulated monopoly, operational scale) | High ⚡ (mining capex, rehabilitation costs) | ⭐⭐ 📊 Stable cash/dividends; limited capital appreciation; long‑term secular risks | Defensive dividend/income play linked to thermal power demand; monitor quarterly output & dividend payouts 💡 |
| HDFC Bank Limited – Market Leader in Private Banking with Strong Loan Growth | High 🔄 (merger integration, regulatory oversight) | Moderate ⚡ (capital adequacy, deposit mobilisation) | ⭐⭐⭐⭐ 📊 Strong loan growth & ROE; NIM and deposit pressure are key risks | Quality banking exposure with growth + returns; track NIM, deposit vs advances, asset quality & CAR 💡 |
| Infosys Limited – IT Services Exporter with Margin Recovery Potential | Moderate 🔄 (global delivery model, client concentration) | Moderate ⚡ (talent, automation/AI investments) | ⭐⭐⭐ 📊 Margin recovery potential (20%+) with 6–8% revenue growth; sensitive to USD/INR | IT services margin‑recovery play; monitor utilization, large deal wins, dollar‑INR and attrition 💡 |
| Maruti Suzuki India Limited – Largest Passenger Car Manufacturer with Cost Advantage | Moderate–High 🔄 (product cycles, supply chain, EV shift) | High ⚡ (capex for new models & EVs, supply chain) | ⭐⭐⭐ 📊 Structural volume growth; margin pressure from input costs and EV transition | Market‑leader auto exposure; cost advantage and volume growth; track volumes, ASPs, raw‑material indices, EV timelines 💡 |
| Wipro Limited – Mid‑Tier IT Services with Specialisation in Cloud and Cybersecurity | Moderate 🔄 (specialisation, cost‑takeout execution) | Moderate ⚡ (talent, automation, nearshoring) | ⭐⭐⭐ 📊 Margin recovery possible (16–18%+); upside if cost initiatives succeed | Mid‑tier IT value play focused on cloud & cybersecurity; watch margins, large deal wins, and utilization 💡 |
| Reliance Industries Limited – Integrated Energy & Retail Conglomerate with Diversified Exposure | Very High 🔄 (energy + retail + telecom + renewables complexity) | Very High ⚡ (massive capex across segments) | ⭐⭐⭐⭐⭐ 📊 Diversified cash generation and optionality (retail/Jio/renewables); earnings sensitive to crude & refining spreads | Diversified blue‑chip for long‑term growth + scale; track Brent, refining margin ($/bbl), Jio Mart metrics and renewables capacity additions 💡 |
Build a Repeatable ₹200 Stock Research Check
The eight companies occupy different analytical categories. Tata Steel is a steel and infrastructure-linked cyclical, with commodity prices, utilisation, realisations and debt as key risks. Bajaj Auto combines two-wheelers, three-wheelers and exports, with product mix, electric adoption and execution at the centre of the review. Coal India belongs to the thermal-energy and dividend context, but policy, production and payout variability matter.
HDFC Bank represents private banking quality, where deposits, advances, NIM, NPAs and capital adequacy deserve priority. Infosys and Wipro are IT-services exporters, exposed to client technology budgets, currency, utilisation, attrition and delivery execution. Maruti Suzuki is tied to passenger-vehicle demand, input costs and the EV transition. Reliance Industries has diversified energy, retail, telecom and renewable businesses, which creates multiple opportunities but also complex valuation and capital-allocation risks.
A repeatable verification process can keep the under-₹200 label in perspective:
- Confirm the live market price: Check the current NSE or BSE quote rather than relying on a historical range. Record the date and IST time.
- Check liquidity: Review trading volume, market depth and bid-ask spreads. Liquidity can change by session, especially during volatile markets.
- Read exchange filings: NSE provides a dedicated corporate filings and announcements platform, while BSE disclosures should also be checked for company-specific updates.
- Review the financial statements: Examine revenue, profit, operating cash flow, free cash flow, debt, working capital and segment performance.
- Compare relevant valuation measures: P/E, price-to-book, enterprise value and dividend yield mean different things across banks, manufacturers, miners and technology companies. Compare each name with appropriate sector peers.
- Inspect governance information: Review promoter disclosures, pledges where applicable, related-party transactions, auditor comments, regulatory actions and changes in senior management.
- Track sector indicators: Steel needs commodity and utilisation data. Autos need volumes and input costs. Banks need credit quality and funding trends. IT services need utilisation, deal wins and currency context.
- Record corporate actions: Splits, bonuses and dividends can change the apparent price and alter comparisons across time.
The distinction between dividend yield, growth potential and momentum matters. Dividend yield describes a distribution relative to price, not a guaranteed total return. Growth potential reflects an analytical expectation about earnings or business expansion, not certainty. Momentum describes recent price behaviour, and it can reverse when market regimes change. Recent Indian market coverage has shown rotation towards auto, realty and PSU banks while FMCG and metals lagged, illustrating why static lists can lose relevance as conditions shift (market-rotation coverage).
Bharatstox can serve as a source of bylined market journalism, timestamped analyst calls with SEBI registration details, plain-language explanations of NSE/BSE filings and mobile-first market data. SEBI's current framework remains an active compliance issue, including its 08 Jan 2025 circular titled “Guidelines for Research Analysts” (SEBI analyst guidelines). Readers can also explore Yield Seeker's diversification strategies for broader education, while remembering that diversification doesn't remove company-specific or market risk.
This is for informational and educational purposes only and not investment advice. Consult a SEBI-registered adviser before investing.
Visit Bharatstox to follow bylined NSE and BSE market journalism, live corporate-filing updates and timestamped analyst calls with visible SEBI registration details. Use its mobile-first market panels and educational explainers to verify price, liquidity, valuation and sector context before forming your own view on stocks under ₹200.
Disclaimer
This article is for informational and educational purposes only and does not constitute investment advice or a recommendation. Investing in securities markets is subject to market risks. Read all related documents carefully before investing.